Channels are scattered
Cards, local transfers, cash rails, and crypto each live in different tools. You need Payment Link, Invoice, QR, API, or Webhook so status lands in one place.
Hong Kong · Cross-border payments
UpayAsia works with cross-border merchants, platforms, and B2B teams that need a compliance review. We help you plan multi-channel collection, large conversion of your own funds, and mid-size payouts to external beneficiaries as separate tracks. Send company, regions, and use case—sales replies with feasibility and a document list.
Who this is for
This page is not a dump of every product name. If you hit the pains below, describe the business clearly—we can tell faster what we can support and what we cannot.
Cards, local transfers, cash rails, and crypto each live in different tools. You need Payment Link, Invoice, QR, API, or Webhook so status lands in one place.
Large conversion of your own funds is not the same as mid-size payments to affiliates or suppliers. Limits, documents, and channels differ—mixing them skews timeline and cost.
Compliant exchanges, gold, FX, insurance intermediaries, licensed finance, or offshore structures usually need a feasibility and document review before any go-live scope.
Finance needs reconciliable settlement and payout records. Engineering needs API and Webhook. Both should share the same status source—not parallel spreadsheets.
Fund flow
Collect first, then handle merchant-owned funds, then pay external parties. Enable the three steps in phases—you do not need everything on day one.
Core services
Each service maps to different amounts, beneficiaries, and review methods. Onboard in the order your business actually needs.
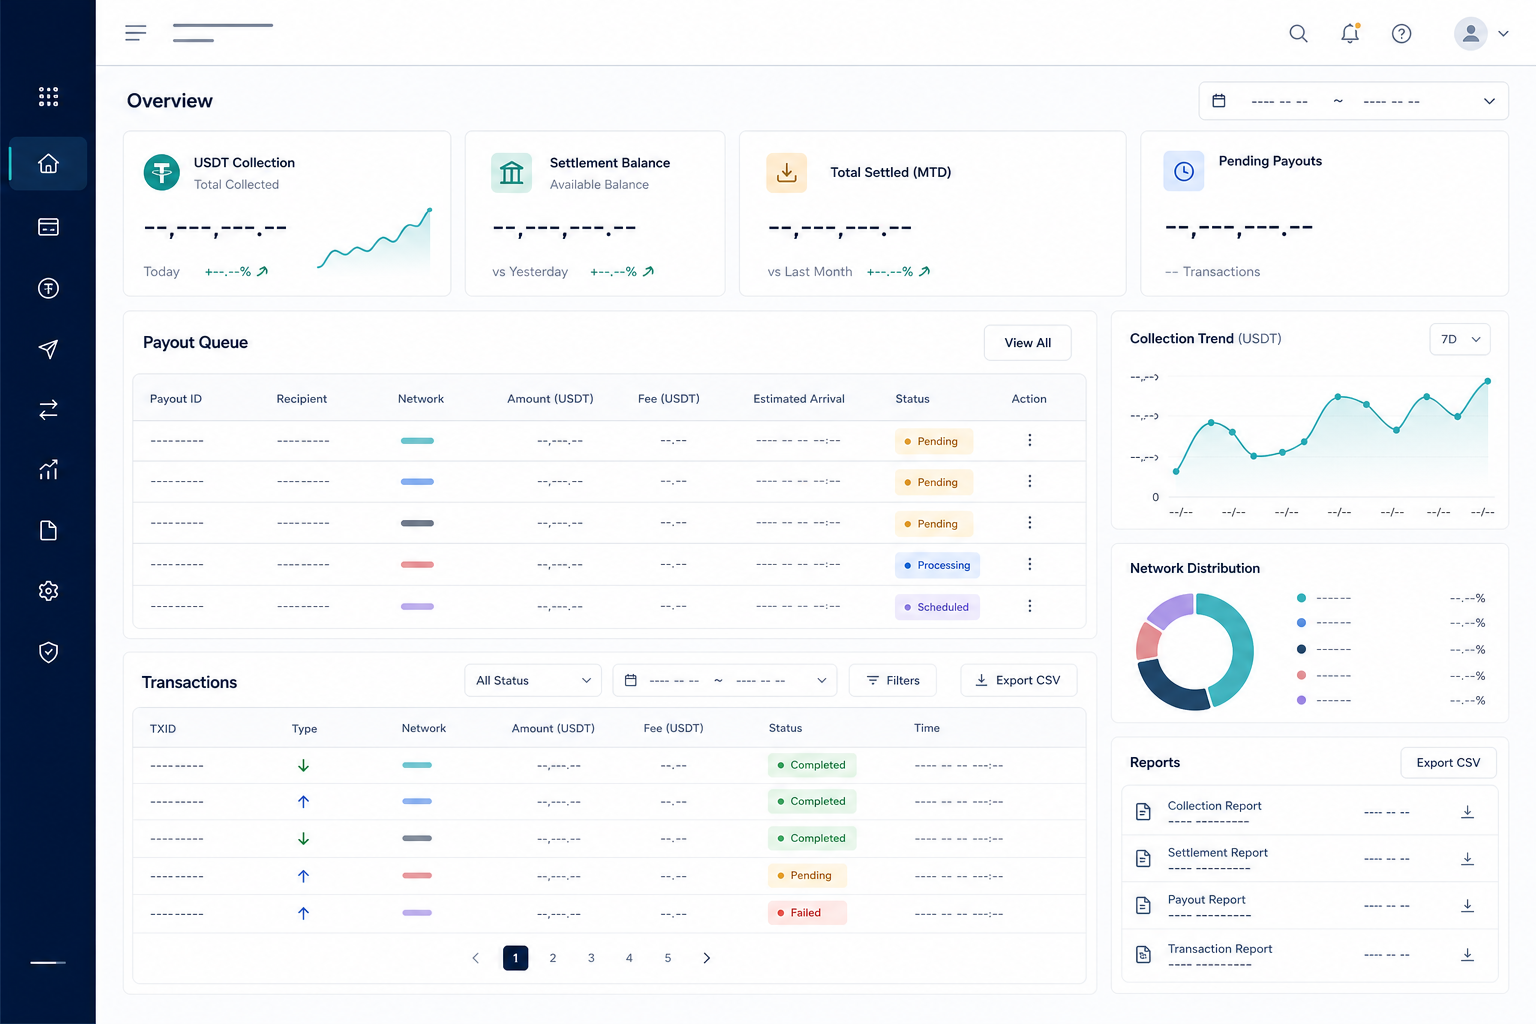
Let customers pay by card, bank/local transfer, fiat cash channels, or crypto. You track everything with Payment Link, Invoice, QR, API, or Dashboard.
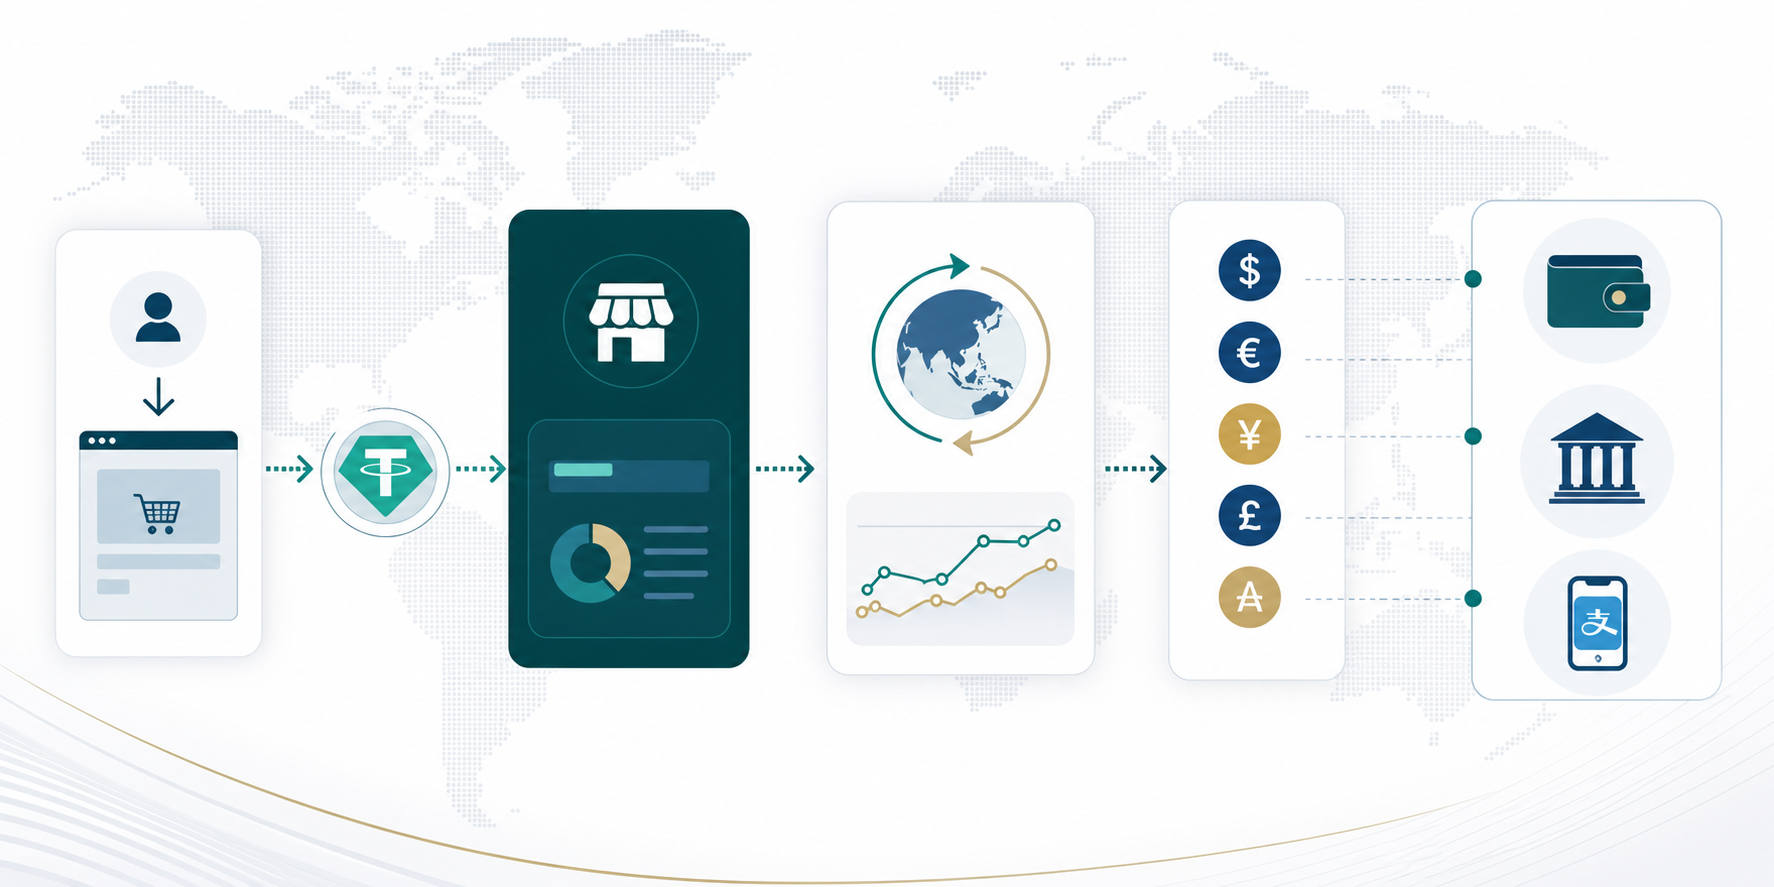
After crediting, convert crypto to USD / HKD / EUR / JPY / CAD as needed, or retain crypto. Built for quoted large tickets with document review and finance reconciliation.

Disburse to end beneficiaries: crypto wallet, multi-currency fiat, and region-enabled local channels. Tickets are usually smaller than settlement; frequency is often higher.
Who should inquire
If you match any row below, bring regions and purpose—that beats asking only for a public rate card.
| Merchant type | Typical need | How we usually help |
|---|---|---|
| Cross-border merchants | Overseas customers want card, bank transfer, fiat cash, or crypto; you need unified tracking and settlement. | Payment Link, Invoice, QR, Dashboard, settlement quotes. |
| Platform businesses | Share revenue with users, affiliates, creators, or partners. | Batch payout, Payout API, status tracking and reports. |
| B2B trade | Large deals need source-of-funds, contracts, invoices, and settlement docs. | Large settlement review, channel quotes, finance reports. |
| Digital services | Multi-region pay-ins, frequent smaller collections, automated notices. | API collection, Webhook, CSV export, transaction monitoring. |
Submit merchant details Special industries: see industry plans
How to start
We do not promise live channels before seeing your materials. Keep the path short so you can prepare once and move.
Extended stack
Beyond payments, some clients need screening, project delivery, or a licensing path discussion. Certain services may be arranged case by case under a licensed name such as Baowang, subject to review and contract.
Name screening, KYC/CDD, corporate due diligence, transaction monitoring, and CRM to support AML operations.
Front/back and API delivery discussions across payments, wealth, lending, embedded finance, blockchain/crypto, insurtech, and regtech.
Application/transfer advisory, ongoing compliance outsourcing, and annual follow-up (MSO, VASP, licensed corporations, and similar paths—case by case).
Ops and API
Lower-frequency merchants can start with Dashboard, Payment Link, or Invoice. Higher-frequency or platform businesses add API and Webhook so finance and engineering share the same status.
Market notes
Still drafting an internal problem list? Skim these two pages, then come back with a concrete scenario.
Covers channel fragmentation, settlement/Payout confusion, manual compliance load, and licensing uncertainty—with a suggested order of work.
Mid- to long-term notes on crypto B2B collection, RegTech, embedded finance, AI risk controls, and VASP supervision—useful for internal alignment.
FAQ
Questions we hear most from sales and onboarding. Details always follow review and contract.
Public offerings include multi-channel collection, large-scale multi-currency settlement, mid-size Payout, AML/client management, Fintech projects, and licensing services. Actual scope depends on merchant data, partner channels, regional rules, and review results. We do not promise unverified volumes or success rates.
Settlement mainly handles large-scale conversion or retention of merchant-owned funds (crypto to USD/HKD/EUR/JPY/CAD, or keep crypto). Payout executes mid-size payments to external beneficiaries via crypto wallets, multi-currency fiat, or local channels. Limits, documents, channels, and timing often differ—evaluate them separately.
Have company registration docs, a short business description, main regions, estimated monthly volume, collection/payout purpose, and any existing licenses ready. After you submit, we reply with a document checklist. You can also start via the contact form, sales@upayasia.com, or +852 5782 3279.
The site references Hong Kong, China, Singapore, Malaysia, Thailand, Vietnam, Indonesia, the Philippines, ASEAN, and global feasibility case by case. Live channels and currencies still depend on merchant review, partner rules, and applicable regulations.
Yes. Many merchants enable Payment Link, Invoice, QR, or API collection first, then add settlement or Payout after review. You do not need every capability on day one.
Fees, limits, settlement directions, and timing are confirmed from merchant data, volume, regions, purpose, and partner-channel results. Contact sales for a feasibility reply—we do not publish fixed public rates before review.
Company name and place of incorporation, main business and target regions, estimated monthly volume, which of collection / settlement / payout you need, and existing licenses if any. Clearer inputs get a faster reply.